Pensioner Car Loans. Pension Income Counts as Income
If a major bank told you a pension is not enough, that is not the full story. We compare lenders who treat Age Pension, DSP, Carers Payment and Veterans' Affairs payments as real income, and structure repayments around your pension cycle.
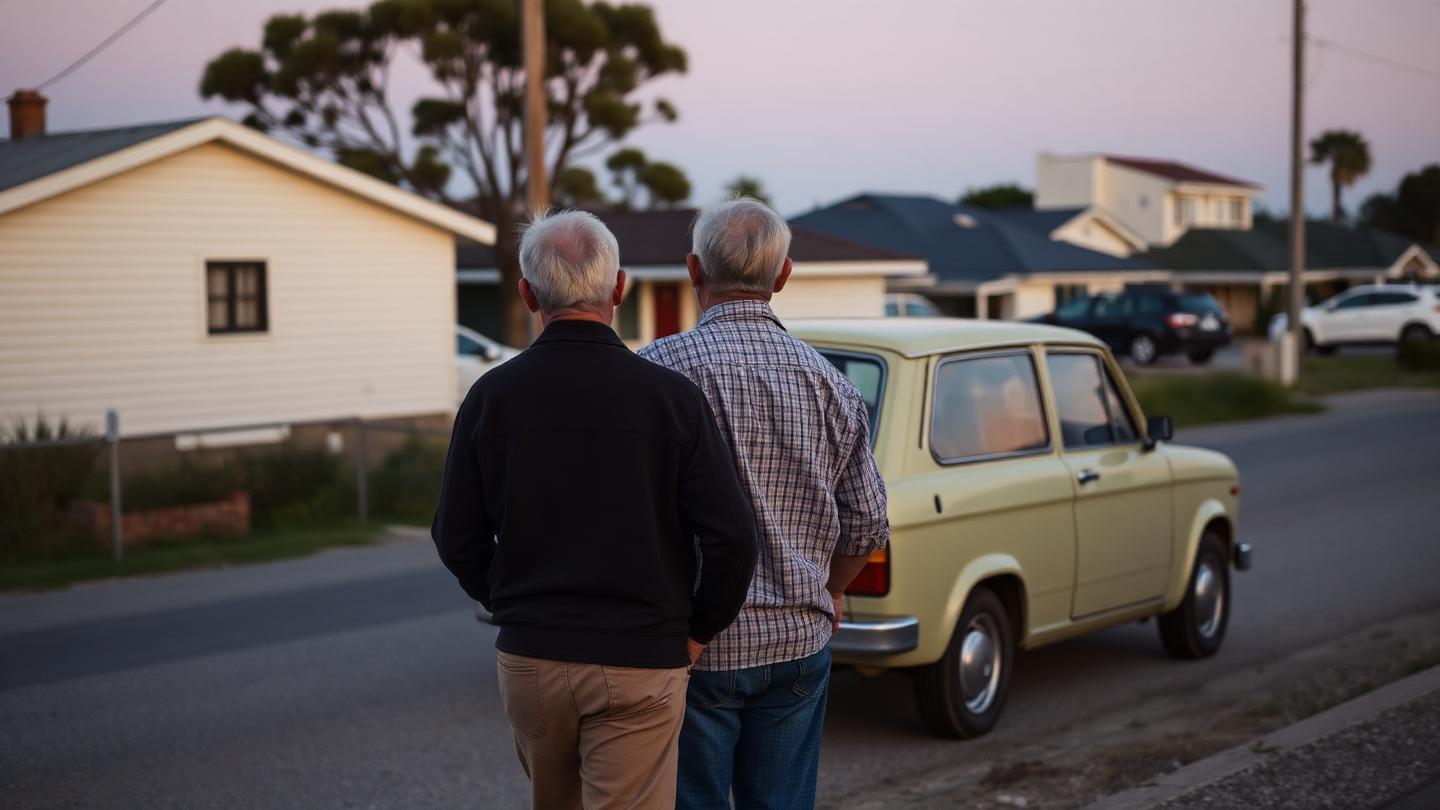
Can you get a car loan on a pension in Australia?
Yes. You can get a car loan on a pension in Australia. Several lenders accept Age Pension, Disability Support Pension, Carers Payment and DVA payments as assessable income, provided the repayment fits your budget after living expenses. Pension income alone can be enough.
- Age Pension, DSP, Carers Payment and DVA income are accepted by lenders on our panel
- Typical pensioner loan sizes run from $5,000 to $25,000 over 3 to 7 years
- Repayment dates can be aligned to your fortnightly pension cycle
- Rates are set by the lender and depend on your circumstances
- A guarantor is not required, though it can widen your options
- Checking your options is free and there are no upfront fees
Reviewed by Simple Loans Editorial Team · Last reviewed
The Simple Loans Editorial Team researches and reviews every car finance guide published on simpleloans.au. Simple Loans holds Australian Credit Licence 509582 and is a member of AFCA.
Why choose Simple Loans.
Pension Income Accepted
Lenders who assess Age Pension, DSP, Carers Payment and DVA income on our panel.
Repayments Around Your Cycle
Direct debits set to land the day after your fortnightly Centrelink payment.
Affordability First
We size the loan so it still leaves a buffer after your living costs, every time.
Specialist Lenders
Access to lenders who write fixed income and retiree finance every week.
Used, New and Mobility Vehicles
Reliable used cars, wheelchair accessible conversions and new vehicles all covered.
Free Assessment
No upfront costs and no obligation to proceed once we show you the options.
Can you get a car loan on a pension?
Yes. Pension income is legitimate, ongoing, government backed income, and lenders on our panel assess it that way. What decides the outcome is not the income type but the responsible lending test set out in the National Consumer Credit Protection Act 2009: the lender must be satisfied the repayment is affordable and does not put you into substantial hardship.
In practice that means the lender looks at your pension, any other income, your rent or mortgage, your living costs and your existing commitments, then works out what is left. If the repayment fits with a sensible buffer, the income type is not the obstacle. Where pensioners get declined is usually a repayment sized to the car rather than the budget.
Which Centrelink and DVA payments are accepted
Policies differ by lender, and this is the main reason a single bank knockback is not the whole picture.
- Age Pension: widely accepted as primary income.
- Disability Support Pension: accepted by several panel lenders as primary income.
- Carers Payment: generally accepted, sometimes alongside other income.
- DVA service and disability pensions: accepted, and often viewed favourably for stability.
- Family Tax Benefit: usually treated as supplementary income only, and sometimes shaded.
- JobSeeker and short term payments: generally not accepted as the primary income.
If your income is a mix, say Age Pension plus part time work, that combination usually improves your borrowing capacity rather than complicating it.
Structuring repayments around your pension
Centrelink pays fortnightly, and most loan defaults among fixed income borrowers come from timing rather than affordability. We ask the lender to set the direct debit for the day after your payment lands, so the repayment clears while the money is there.
A few practical rules we apply when sizing a pensioner car loan:
- Keep the repayment under about ten to fifteen per cent of your fortnightly pension.
- Budget separately for registration, compulsory third party, comprehensive insurance, fuel and servicing. On a fixed income these costs matter as much as the repayment.
- Favour a reliable vehicle three to ten years old with a full service history over a cheaper car that will need work.
- Choose the shortest term you can comfortably afford, because a longer term lowers the repayment but raises total interest.
Getting approved: what actually helps
Small changes to your application often move the outcome more than shopping for a headline rate.
- Clean up three months of statements. Lenders read them. Regular buy now pay later or gambling transactions are the most common cause of a decline.
- Clear small debts first. Closing a $1,500 credit card can free more capacity than a $1,500 deposit.
- Declare every income source. Part time work, rental income, superannuation drawdowns and a partner's income all count.
- Consider a joint application. If your partner also receives a pension, a joint loan raises the assessable income.
- Apply once. Multiple applications in a short period leave multiple enquiries on your file and read as financial stress.
We check the fit against lender policy before anything is lodged, so your file goes to one lender that is likely to say yes.
Your protections as a pensioner borrower
Every loan we arrange is regulated credit. Simple Loans holds Australian Credit Licence 509582 and is a member of the Australian Financial Complaints Authority. That means you are entitled to a written preliminary assessment on request, to hardship consideration if your circumstances change, and to free external dispute resolution through AFCA if something goes wrong.
If a repayment ever becomes unaffordable, contact the lender and tell them early. Under the National Credit Code you can ask for a hardship variation, and lenders must consider it. We will help you make that request at no cost, whether or not the loan is still recent.
This page is general information and does not take your personal circumstances into account.
How it works.
Apply Online in 60 Seconds
Fill out our simple online form, no paperwork, no obligations, and zero upfront fees.
We Compare 50+ Lenders
Our finance comparison tools search our panel of banks and specialist lenders to find the best rate for your situation.
Drive Away Happy
Once approved, funds are settled fast, often same day. You drive away with finance sorted.
Frequently asked questions.
Can you get a car loan on a pension?
Yes. Several lenders on our panel accept pension income, including the Age Pension, Disability Support Pension, Carers Payment and Veterans' Affairs payments. The lender checks that the repayment is affordable after your living expenses rather than rejecting you for the income type.
Which Centrelink payments do lenders accept?
Commonly accepted payments are the Age Pension, Disability Support Pension, Carers Payment, Carer Allowance in some cases, and Department of Veterans' Affairs service and disability pensions. JobSeeker and short term payments are generally not accepted as the primary income. Each lender sets its own policy, so we match you to the one that suits your income mix.
How much can a pensioner borrow for a car?
Most pensioner car loans sit between $5,000 and $25,000. The figure depends on your total income, your existing commitments and the buffer left over after living expenses. Adding part time work, rental income or a partner's income usually lifts the amount available.
Do I need a deposit?
Not always. Some lenders will fund the full purchase price for a suitable vehicle, while others prefer a deposit of five to ten per cent. Even a small deposit reduces the amount financed and can improve the rate you are offered.
Can I get a car loan on the Disability Support Pension?
Yes. DSP is accepted by several lenders on our panel. As long as the repayment fits comfortably alongside your living expenses, finance is available. Wheelchair accessible vehicles and mobility conversions can usually be included in the loan amount.
Is there an age limit on pensioner car loans?
There is no upper age limit under Australian credit law. Lenders must be satisfied you can meet repayments for the full term without substantial hardship, so for longer terms some lenders ask how the loan will be repaid if your circumstances change. A shorter term often resolves this.
Will applying hurt my credit score?
A free assessment with us does not put an enquiry on your credit file. An enquiry is only recorded once you agree to lodge a formal application with a chosen lender, which is why we compare first and apply once.
What documents do pensioners need?
Usually photo ID, a current Centrelink income statement or DVA payment summary, and three months of bank statements showing the pension being paid in. If you have other income, add recent payslips or a rental statement.
Can I get a car loan on a pension with bad credit?
Often yes. Lenders on our panel write finance for people with past defaults, and in some cases a discharged bankruptcy or Part 9 arrangement. The rate will be higher than a clean file, and the loan still has to be affordable on your pension.
Ready to get started.
Free assessment, no upfront costs. We compare 50+ lenders to find you the best deal.
Simple Loans is a finance comparison tool. Holder of Australian Credit Licence No. 509582. All applications are subject to lender approval. Terms, conditions, fees and charges apply. This information is general in nature.