Take Control of Your Debt

Debt Consolidation Loans

Tired of juggling multiple debts? Combine your credit cards, personal loans, and other debts into one simple, lower-interest loan. One payment. One rate. One clear path to debt-free.
What Debts Can You Consolidate?

Most unsecured debts can be rolled into one consolidation loan. Here's what we commonly help people consolidate.
Credit Cards

High-interest credit card debt is one of the most expensive, consolidating can save thousands.
Personal Loans

Multiple personal loans can be combined into one lower-rate loan with a single repayment.
Payday Loans

Break the cycle of payday loans with affordable long-term finance that reduces your payments.

Store Finance

Buy now pay later and store cards often have high rates, consolidate for savings.

Benefits of Debt Consolidation

Consolidating your debts can transform your finances. Here's how.

Consolidate debts

Lower Interest Rate

Replace multiple high-rate debts with one loan at a lower rate

Less stress

One Simple Payment

Stop juggling multiple payments, just one direct debit each month

1-7 year terms

Clear End Date

Know exactly when you'll be debt-free with a fixed loan term

Avg. $5,000+

Potential Savings

Lower rates and structured payments can save thousands

How Debt Consolidation Works

We make consolidating your debts simple with our 4-step process.

1

List Your Debts

Tell us about your current debts, credit cards, loans, BNPL, etc.

2

Get my rate

We compare 50+ banks and lenders to find your best consolidation rate.

3

We Handle the Rest

Once approved, we can pay off your debts directly for simplicity.

4

One Easy Payment

Enjoy one lower payment each month with a clear debt-free date.

See How Much You Could Save

Many Australians save thousands by consolidating high-interest debts into one lower-rate loan. Use our calculator to estimate your potential savings.
Credit cards and store finance typically charge much higher interest than a personal loan
Payday and short-term loans can be especially expensive over time
One predictable monthly repayment, one due date, one lender to deal with
Consolidation rates across 50+ lenders, your actual rate is confirmed by a specialist
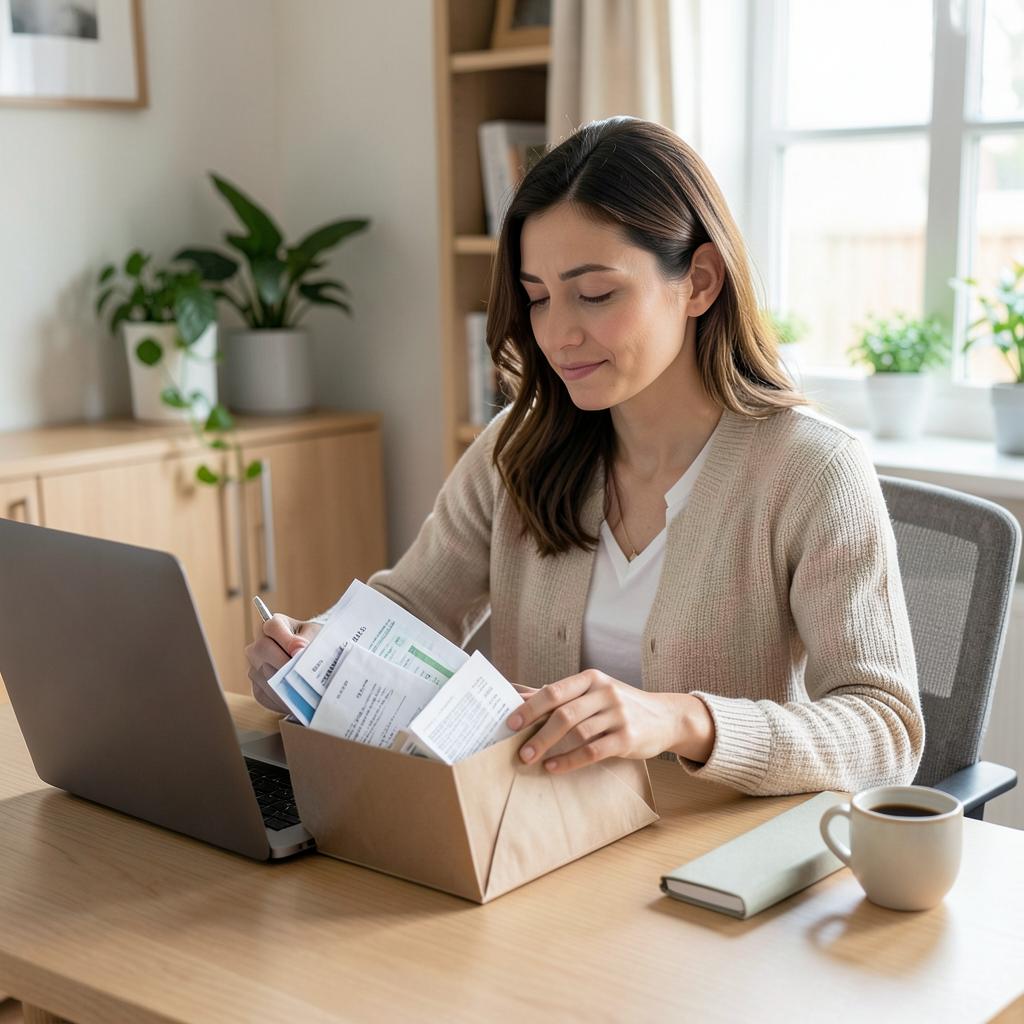
Woman organising bills and statements into one folder at a home desk

Simplify

Many repayments, one loan

One lender, one due date, one balance

Compare 50+ Banks & Lenders

We compare consolidation rates from Australia's leading lenders.

Our lender partners

Debt Consolidation FAQs

Common questions about consolidating your debts.

What is debt consolidation?

Debt consolidation involves taking out a new loan to pay off multiple existing debts, such as credit cards, personal loans, or buy now pay later accounts. You end up with one loan, one interest rate, and one monthly payment instead of juggling multiple debts.

Will debt consolidation save me money?

It can, if your new loan has a lower interest rate than your existing debts. Replacing high-interest credit card debt with a lower-rate consolidation loan could save you thousands. Consider all fees and ensure you don't extend the loan term unnecessarily.

Can I consolidate debt with bad credit?

Yes! While you may not qualify for the lowest rates, specialist lenders work with people who have credit issues. We can help find lenders who focus on your current situation and ability to repay rather than past credit problems.

What debts can I consolidate?

Most unsecured debts can be consolidated including credit cards, personal loans, store cards, buy now pay later (Afterpay, Zip), payday loans, and even some overdue bills. You typically can't consolidate secured debts like mortgages through a personal loan.

How much can I borrow for debt consolidation?

Consolidation loans typically range from $5,000 to $75,000 depending on your income, credit history, and total debts. We'll help you work out exactly how much you need to clear your debts completely.

Is a secured or unsecured loan better for consolidation?

Both have advantages. Secured loans (using a car as security) offer lower rates but put your asset at risk. Unsecured loans don't require collateral but have slightly higher rates. The best choice depends on your circumstances.